Jurisdiction · Cyprus Tax Advantages

Aplacebuilttohold.

A competitive 15% corporate tax rate, more than 67 double tax treaties, an EU-approved IP Box and a 17-year non-domicile regime — the Cyprus framework, made workable for groups, founders and families.

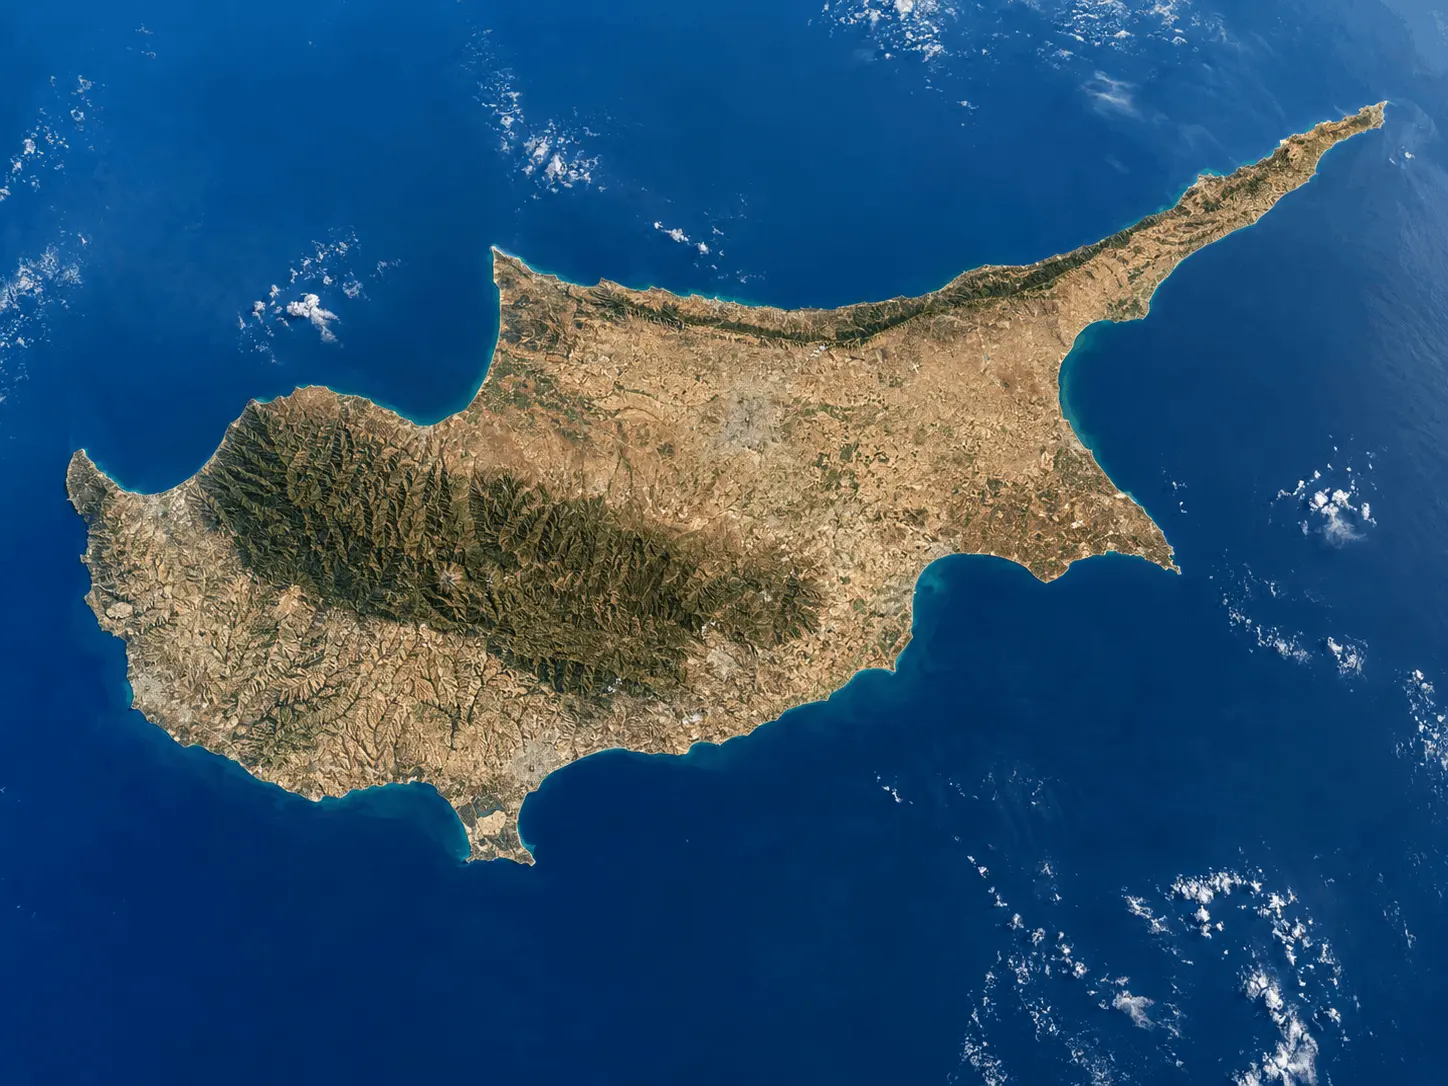
A.T.N. & Partners — satellite view of Cyprus in the eastern Mediterranean
At a glance
  • 0115% corporate tax rate
  • 0267+ double tax treaties
  • 03EU-approved IP Box
  • 0417-year non-dom regime
Headline numbers

Four numbers that explain why Cyprus.

The Cyprus regime is built around a small number of headline figures — the rate, the treaty count, the IP exemption and the non-dom horizon. The rest is structuring.

  1. 0115%Corporate tax rateOne of the most competitive rates inside the EU, applied to taxable profits
  2. 0267+Double tax treatiesExtensive treaty network covering the EU, the UK, the US, China, India, the Gulf and beyond
  3. 0380%IP Box exemptionUp to 80% exemption on qualifying profits from qualifying IP — effective rate as low as 2.5%
  4. 0417yrsNon-dom horizonNon-domicile status available for 17 years, with no Special Defence Contribution on dividends or interest
Also in the framework
  • No withholding tax on outbound dividends
  • Securities-sale exemption from corporation tax
  • Notional Interest Deduction on new equity
  • No inheritance, wealth or gift taxes
  • 5-year carry-forward of tax losses
  • 50% income exemption for qualifying new arrivals
Advantages

Four themes, twelve points, one coherent regime.

The Cyprus framework groups naturally into four themes. Open one to see how the rules fit together and what the regime actually delivers in practice.

A competitive corporate tax rate inside the EU, with material exemptions on the gains that matter most to investors and operators.

In the regime

  • 15% corporate tax rate within a competitive EU framework
  • Profit from the sale of securities exempt from corporation tax
  • No capital gains on assets situated outside Cyprus
  • Five-year carry-forward of tax losses, with group relief available

Treaty network

Global reach, from a small EU island.

More than 67 double tax treaties anchor Cyprus inside the global flow of dividends, interest, royalties and gains. The list below is indicative — the structure determines which treaty actually applies.

PositionCyprus — at the crossroads of Europe, the Middle East and Africa.
  1. European Union

    EU & EEA · 10 partners
    • Germany
    • France
    • Netherlands
    • Ireland
    • Italy
    • Spain
    • Luxembourg
    • Malta
    • Poland
    • Sweden
  2. Americas

    North & South · 5 partners
    • United States
    • Canada
    • Mexico
    • Brazil
    • Argentina
  3. Asia & Middle East

    Trade & investment · 10 partners
    • United Kingdom
    • Switzerland
    • UAE
    • Saudi Arabia
    • India
    • China
    • Singapore
    • Hong Kong
    • Japan
    • Israel
  4. CIS, Africa & beyond

    Emerging markets · 8 partners
    • Russia
    • Ukraine
    • Kazakhstan
    • Georgia
    • South Africa
    • Egypt
    • Mauritius
    • Seychelles
How we apply it

From diagnosis to year-on-year maintenance.

The regime only delivers when it is mapped to a specific structure. Four steps, partner-led, with the same team from first call through annual filings.

01

Diagnose

Residence, ownership chain, cash flows and the people involved — we map them to the regime and identify the levers that matter.
02

Structure

We design the holding, IP and operating layers — share capital, participation, NID and the treaty position needed to anchor the structure.

03

Implement

Incorporations, rulings where useful, IP Box documentation, treaty residency certificates and the filings that put the regime to work.

04

Maintain

Annual returns, audits, defence contribution reviews and the year-on-year treaty claims that keep the structure in good standing.

Who it serves

Built for holding groups, IP owners, individuals and funds.

Holding & finance structures

Ultimate or intermediate holding companies for groups operating across EU and treaty jurisdictions — with predictable dividend, interest and exit treatment.

IP & technology

Software, life-sciences and brand owners using the modernised IP Box for qualifying assets, supported by clear OECD-aligned documentation.

Individuals & family offices

Non-domiciled residents, relocating executives and family offices seeking predictable personal tax with no inheritance, wealth or gift taxes.

Funds & investment vehicles

AIFs, RAIFs and corporate investors using Cyprus as a regulated, treaty-rich platform for cross-border investment and exits.

Important note

General information, not advice.

This information is general in nature and should not be relied upon as professional advice. Please contact A.T.N. & Partners for advice based on your specific circumstances.

Engage

Tell us the structure, and we will map the regime to it.

A brief on the group, the cash flows and the people involved is enough for a partner to come back within one business day with a view on how the Cyprus regime applies and where the value is.

CorporateHoldings · Group structuring · Exits
IndividualsNon-dom · Relocation · 50% exemption
IP & innovationIP Box · Notional Interest Deduction
OfficeNavarino Business Centre, 18 Navarinou Street, Nicosia
Request an opinion